One of the clearest signals in September’s South Florida housing data is how little single-family inventory remains relative to the pace of sales. Months of supply fell across the region and in every county compared with a year earlier, leaving Palm Beach especially tight and Miami-Dade the least constrained of the three. That limited supply provides important context for evaluating softer sales and pending activity.
Single-Family Months of Supply: September 2026
South Florida MSA and county comparison | September 2026
Source: Florida Realtors® SunStats | September 2026. Year-over-year percentage declines are calculated from the reported current and prior-year months of supply and rounded to the nearest whole percent.
Key Statistic: 4.2 Months of Supply
↓ 25% Year Over YearRegional Executive Summary
South Florida’s single-family market remained supply-constrained in September, with just 4.2 months of inventory across the Miami–Fort Lauderdale–West Palm Beach MSA, down from 5.6 months a year earlier. Active inventory was 18% lower year over year, while homes reached contract faster, with median days on market declining from 50 to 41 days. The regional median sale price increased 3.0% to $659,000.
At the same time, transaction activity softened. Closed single-family sales declined 4.7%, while new pending sales fell 13%. The combination of low supply and weaker pending activity suggests that September cannot be characterized by inventory conditions alone; both limited selection and slower near-term contract activity are influencing the number of transactions moving through the market.
Townhouses and condos remained considerably better supplied, with 9.9 months of inventory across the region. Active inventory declined 11%, closed sales fell 5.6%, and new pending sales decreased 9.6%. The regional median sale price still increased 1.4% to $330,000, but county-level performance varied substantially.
Palm Beach County posted the tightest single-family supply at just 3.6 months and the strongest single-family price growth at 6.7%. Broward’s condo market showed the weakest performance, with closed sales down 13%, pending sales down 15%, and the median sale price down 15%. Miami-Dade remained the most supplied county in both property categories, although condo closed sales increased slightly year over year.
South Florida’s single-family market remains supply-constrained at just 4.2 months of inventory. September’s weaker pending-sales activity matters, but it is occurring in a market with substantially less available supply than a year ago.
South Florida MSA
Low Single-Family Supply Meets Softer Contract Activity
| Metric | Single-Family Homes | Townhouses & Condos |
|---|---|---|
| Active Inventory | 13,368 (down 18%) | 27,146 (down 11%) |
| Median Days on Market | 41 days (down from 50) | 64 days (down from 72) |
| Months of Supply | 4.2 months (down from 5.6) | 9.9 months (down from 11.6) |
| Closed Sales | 2,930 (down 4.7%) | 2,542 (down 5.6%) |
| New Pending Sales | 2,798 (down 13%) | 2,585 (down 9.6%) |
| Median Sale Price | $659,000 (up 3.0%) | $330,000 (up 1.4%) |
The regional single-family market remains relatively tight, with months of supply falling 25% from 5.6 months a year ago to 4.2 months. Inventory also declined 18%, while median days on market shortened and the median sale price increased. However, pending sales fell substantially more than closed sales, making near-term contract activity an important counterpoint to the region’s low supply.
Strategic takeaway: South Florida’s single-family market continues to offer buyers relatively limited selection, but September also shows softer contract activity. Low supply remains supportive of sellers, while accurate pricing is increasingly important as buyers become more selective.
Broward County
Tight Single-Family Supply and a Weaker Condo Market
| Metric | Single-Family Homes | Townhouses & Condos |
|---|---|---|
| Active Inventory | 4,351 (down 18%) | 9,582 (down 12%) |
| Median Days on Market | 39 days (down from 48) | 69 days (down from 73) |
| Months of Supply | 4.2 months (down from 5.4) | 10.2 months (down from 11.6) |
| Closed Sales | 974 (down 7.1%) | 851 (down 13%) |
| New Pending Sales | 922 (down 15%) | 889 (down 15%) |
| Median Sale Price | $641,500 (up 2.4%) | $235,000 (down 15%) |
Broward’s single-family months of supply fell from 5.4 to 4.2 months, a decline of roughly 22%, while active inventory was 18% lower than a year ago. Homes also reached contract faster and the median sale price increased 2.4%. The condo market was notably weaker, with both pending and closed sales declining sharply and the median sale price 15% below September 2025.
Strategic takeaway: Broward’s single-family market remains relatively tight, but weaker pending sales suggest buyers are not moving forward at the same pace as last year. Condo sellers face a more competitive environment and should pay close attention to pricing, building condition and ownership costs.
Palm Beach County
The Region’s Tightest Supply and Strongest Pricing
| Metric | Single-Family Homes | Townhouses & Condos |
|---|---|---|
| Active Inventory | 4,481 (down 20%) | 5,858 (down 15%) |
| Median Days on Market | 43 days (down from 51) | 53 days (down from 65) |
| Months of Supply | 3.6 months (down from 5.0) | 6.8 months (down from 8.8) |
| Closed Sales | 1,132 (down 2.7%) | 782 (down 4.3%) |
| New Pending Sales | 1,062 (down 14%) | 760 (down 4.8%) |
| Median Sale Price | $656,000 (up 6.7%) | $310,000 (up 3.3%) |
Palm Beach had the region’s lowest single-family supply at just 3.6 months, down 28% from 5.0 months a year earlier. Active inventory fell 20%, while the median sale price increased 6.7%, the strongest single-family price gain among the three counties. Closed sales declined only 2.7%, although new pending sales were down 14%.
Strategic takeaway: Palm Beach continues to show the strongest combination of limited supply and price growth. Buyers face the least single-family selection in the region, although weaker pending sales suggest that affordability and property-specific value remain important.
Miami-Dade County
More Supply Than Broward and Palm Beach, but Still Below Last Year
| Metric | Single-Family Homes | Townhouses & Condos |
|---|---|---|
| Active Inventory | 4,536 (down 17%) | 11,706 (down 7.2%) |
| Median Days on Market | 41 days (down from 50) | 67 days (down from 75) |
| Months of Supply | 5.1 months (down from 6.5) | 12.3 months (down from 14.0) |
| Closed Sales | 824 (down 4.7%) | 909 (up 0.6%) |
| New Pending Sales | 814 (down 12%) | 936 (down 7.5%) |
| Median Sale Price | $692,000 (up 4.1%) | $417,090 (down 0.7%) |
Miami-Dade had the region’s highest single-family supply at 5.1 months, but that was still roughly 22% below the 6.5 months recorded a year earlier. Active inventory declined 17%, median days on market shortened, and the median sale price increased 4.1%. The condo market remained substantially more supplied at 12.3 months, while closed sales increased slightly by 0.6% year over year.
Strategic takeaway: Miami-Dade offers buyers more single-family and condo selection than the other two counties, but supply has still tightened considerably from last year. Condo buyers retain the greatest negotiating flexibility in this market.
What the Market Means for You
For Buyers
Single-family buyers continue to face relatively limited supply throughout South Florida, especially in Palm Beach and Broward. Fewer available homes can reduce the number of suitable choices even when overall sales activity slows. Buyers should remain prepared to move when a well-priced property meets their needs, while still evaluating condition and value carefully. Condo buyers generally have more selection, particularly in Miami-Dade and Broward.
For Sellers
Low single-family supply remains favorable for sellers, but September’s decline in pending sales shows that buyers are still selective. Competitive pricing and strong property presentation remain important even in a low-inventory environment. Condo sellers face greater competition and should pay particular attention to comparable listings, building condition, association finances, insurance and assessments.
Key Takeaways
- Single-family supply remains limited: The South Florida MSA had just 4.2 months of supply in September, down 25% from 5.6 months a year ago.
- Palm Beach is the tightest market: Single-family supply fell to 3.6 months, while the median sale price increased 6.7%.
- Pending sales weakened: Regional single-family pending sales declined 13%, showing that tight inventory is not the only factor affecting transaction volume.
- Condo buyers have more selection: Regional townhouse and condo supply measured 9.9 months, compared with 4.2 months for single-family homes.
- Broward condos were the weakest segment: Closed sales fell 13%, pending sales declined 15%, and the median sale price was down 15% year over year.
Regional Outlook
South Florida enters the fall market with significantly tighter single-family supply than a year ago. Months of supply declined across the region and in all three counties, while active inventory remains substantially lower. These conditions continue to limit buyer choice and provide support for well-positioned single-family listings.
September also introduced a more cautious signal through weaker pending sales. The next several reports will help determine whether that decline represents a short-term pause or a broader shift in buyer activity. Changes in inventory, pending sales, marketing times and pricing will be particularly important as South Florida moves toward the winter selling season.
About the Data
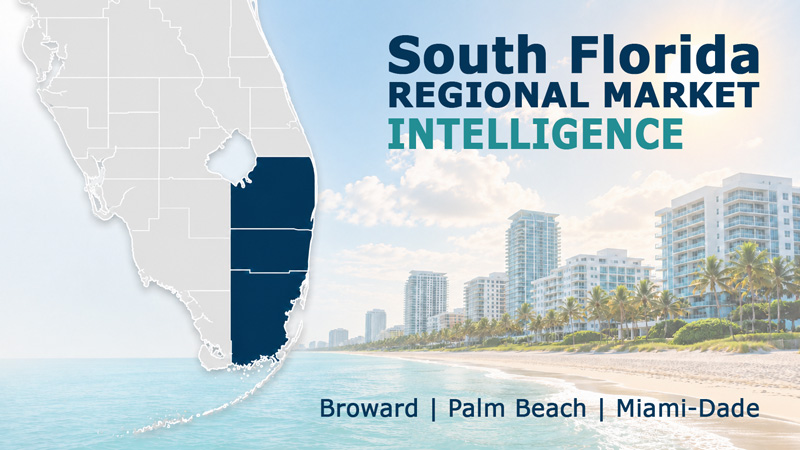
This report is based on September 2026 Florida Realtors® SunStats data for the Miami–Fort Lauderdale–West Palm Beach MSA and Broward, Palm Beach and Miami-Dade counties.
The percentages and prior-year figures shown in the tables are year-over-year comparisons. The percentage declines displayed in the featured months-of-supply chart are calculated from Florida Realtors’ reported current and prior-year months of supply and rounded to the nearest whole percentage point.
Median sale prices reflect the mix of properties sold during each reporting period and should not be interpreted as direct measures of individual property appreciation. Regional and county statistics provide broad market context and should not be used as a valuation of a specific home, condominium building or neighborhood.